

Ollo Credit Card Mobile App
by Merrick Bank
3.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.6
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
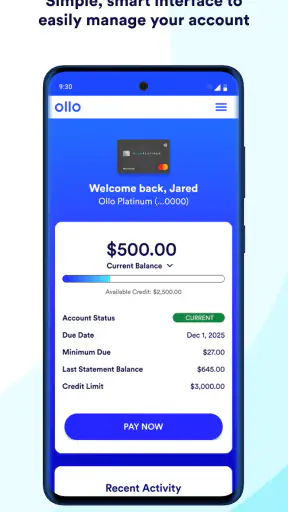
 Analysis by Getfullapps
Managing a credit card from a phone sounds simple, but the quality of the experience depends on whether the app helps me complete routine tasks quickly and understand what is happening with my account. I spent time looking at Ollo Credit Card Mobile App from that practical point of view: checking whether it feels suitable for everyday account management, where it is more convenient than older alternatives, and when a different approach may be better.
This is a free finance app from Merrick Bank for people who use an Ollo credit card. Its purpose is focused rather than broad. I would not approach it as a general budgeting tool, a banking replacement, or a marketplace for financial products. I see it as the mobile doorway to card management, which makes reliability, clarity, and the speed of common actions more important than a long list of extra features.
What I would check before choosing it
My first decision criterion is fit. The app makes the most sense if your main financial relationship is an Ollo credit card and you want to handle that relationship from a phone. If you are looking for a complete money-management system that combines several banks, tracks investments, builds a detailed spending plan, or gives a wide view of your finances, this is probably too narrow for your needs.
The next question is how often you perform small account tasks. A dedicated card app can be useful when you want to check a balance before buying something, review recent activity after a purchase, or deal with an account task without opening a desktop browser. Those moments are not dramatic, but they are exactly where a focused mobile experience earns its place.
I also consider trust and familiarity. Because Merrick Bank develops the app, an existing cardholder may prefer using the official mobile channel connected to the card rather than relying on an unrelated finance service. That does not automatically make every interaction perfect, but it reduces the confusion that can come from trying to manage a card through several disconnected tools.
The app is rated for Everyone, so its presentation is intended for a broad audience. That should not be confused with the idea that every financial decision is suitable for every person. A simple interface can make account access easier, but users still need to read transaction details, monitor their obligations, and protect their sign-in information.
Its current version is 4.49.11, and the app runs on Android devices using at least version 6.0. That broad system compatibility is helpful if you keep an older phone for financial tasks or do not replace devices frequently. I would still check that the phone itself receives security updates, because compatibility alone is not the same as good device security.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The everyday test matters more than the feature list
Imagine I am at a shop and cannot remember how much available room I have on the card. The useful workflow is not complicated: open the app, authenticate, look at the account information, and decide whether the purchase fits my plan. Later, I might return to review the transaction and make sure the amount looks familiar. That is a realistic reason to keep a card app installed, even if I use another app for my wider budget.
A second scenario is monthly review. I can use the phone as a quick checkpoint after receiving a statement, comparing recent activity with receipts and noting anything that needs attention. The important habit is not merely opening the app; it is using the account view to catch mistakes while a purchase is still easy to remember.
One useful but easily overlooked distinction is that a card-management app and a budgeting app answer different questions. The former helps me understand the state of one card. The latter helps me understand where my money goes across accounts. Trying to force Ollo Credit Card Mobile App to do the second job would create frustration, while pairing it with a separate budgeting method can be sensible.
Where the focused design works well
The strongest point is its narrow purpose. When I only need to deal with my Ollo card, a dedicated app is more direct than opening a general financial dashboard and searching through several accounts. That focus can also make the app easier to explain to a family member who only needs card access and does not want a complicated money-management system.
I also like the idea of separating card administration from everyday spending analysis. A general personal-finance app may be excellent for trends and categories, but I would still want the issuer’s own channel available for account-specific tasks. Keeping those roles separate gives me a clearer mental model: one place for the card relationship, another place for broader planning if I need it.
The app has reached over one hundred thousand installs, which suggests that it is not an obscure experiment with no practical audience. Its average rating is 3.6 from roughly three hundred ratings, so the public response is mixed rather than universally enthusiastic. I read that as a reason to keep expectations realistic: the app may be useful for its intended job, but convenience will depend on how smoothly it fits each user’s device and routine.
Another advantage is cost. The app itself is free, so trying it does not require a separate purchase. That makes the decision easier for an existing Ollo cardholder: the main question is whether the mobile workflow is helpful, not whether the app adds another subscription to the household budget.
Small habits that make the app more useful
I would use it as a verification tool instead of waiting until the end of a billing cycle to remember what happened. After a larger purchase, checking the account later can confirm that the posted amount matches the receipt. This is especially useful when a transaction changes from pending to completed, because the timing and final amount may not be what I initially remember.
I would also avoid treating the displayed balance as permission to spend without thinking. A card balance is an account snapshot, not a personal budget. Before making a purchase, I would compare the app’s information with money I have set aside and with any payments already planned. That simple extra step prevents a focused card app from encouraging overconfidence.
For shared household finances, I would decide in advance who is allowed to access the account and on which device. Installing the app on every available phone may seem convenient, but financial access should be deliberate. A dedicated device lock, careful sign-in practices, and avoiding account access on borrowed phones matter more than shaving a few seconds off the login process.
I would also keep a second record for important disputes or payment decisions. The app can be the place where I notice a problem, but I would save relevant receipts and note the date of my follow-up separately. That workflow is more dependable than assuming that seeing a transaction in an app is the same as documenting the issue.
How it compares with the usual alternatives
I find the choice between a dedicated card app and a browser comes down to how often I check in: a quick account glance is easier to make a habit when access is already on my phone, while occasional users may prefer not to add another app. Either way, I’d keep a separate budgeting method for the bigger picture; the next section looks at where this focused approach fits alongside broader finance tools.
Compared with using a mobile browser
The first alternative is simply managing the card through a browser. That can be preferable if I rarely access the account, if I do not want another app installed, or if I use a computer for all financial tasks. A browser can also be more comfortable when I need a larger screen for careful reading.
The dedicated app is more attractive for short, repeated checks. I do not have to remember a web address or navigate through a browser tab that may have expired. On a phone, that directness can make the difference between checking a transaction immediately and putting it off until later.
The trade-off is that an app becomes part of my device environment. I need to keep the phone protected, install updates responsibly, and be comfortable with the app’s behavior on my particular device. Someone who prefers minimal apps may reasonably choose the browser instead.
Compared with a general budgeting service
Budgeting services are better when the goal is to combine spending from multiple accounts, view categories, or plan household cash flow. They can give a wider picture than a single-card app. If my main question is whether dining, transport, or subscriptions are taking too much of my monthly income, I would look beyond this app.
Ollo Credit Card Mobile App is better suited to the narrower question of what is happening with the Ollo card itself. That distinction is important because broader tools sometimes depend on connections to financial institutions, while the issuer’s own app is designed around its card relationship. I would not choose one as a complete substitute for the other unless my needs are unusually limited.
Compared with a desktop account portal
A desktop portal may win when I want to sit down and review several statements, organize records, or work through a longer financial task. The larger display reduces the need to scroll and makes it easier to keep notes or receipts nearby.
The mobile app wins in moments where waiting for a computer is inconvenient. A quick check before a purchase or a review after a notification is exactly where a phone has an advantage. My preferred setup would be to use mobile access for immediate awareness and a larger screen when I need a more deliberate review.
Who should skip it
I would skip it if I do not have an Ollo credit card, because the app’s value is tied to that specific card relationship. I would also look elsewhere if I expect detailed financial planning, investment monitoring, account aggregation, or a sophisticated spending dashboard. Installing a focused card app and then criticizing it for not being a full financial suite would be unfair, but it would still be the wrong purchase decision for those needs.
I might also choose a browser if I access the account only occasionally and want to keep my phone uncluttered. Likewise, users with older or heavily customized devices should judge the real experience on their own hardware rather than assuming that broad operating-system support guarantees perfect performance everywhere.
What switching really involves
Moving from browser access to the app is not a major financial commitment because the app is free, but there is still a small adjustment cost. I would need to establish a comfortable sign-in routine, decide whether the phone is secure enough for account access, and learn where the information I use most often appears. The benefit is convenience; the cost is adding another access point to manage responsibly.
Moving from a general finance app to this one is different. I would not expect the dedicated app to replace my broader records. Instead, I would keep the budgeting method for planning and use the card app for account-specific checking. That two-tool arrangement may feel less tidy, but it can be more accurate because each tool has a clearly defined job.
If I stopped using it later, I would not consider that a failure. A mobile app should earn its place by reducing friction. If browser access is just as easy for my routine, or if I rarely need card information, removing the app may be sensible. The important thing is to preserve access to the account and continue monitoring it, regardless of which channel I prefer.
My recommendation for different users
For an existing Ollo cardholder who checks the account from a phone, I would recommend trying it. The free price removes the biggest barrier, and the focused design matches ordinary tasks such as checking activity and staying aware of the account. I would especially consider it worthwhile if I often make purchases away from home or tend to postpone account reviews when access is inconvenient.
For someone who already uses a strong budgeting system, I would recommend it as a companion rather than a replacement. Keep the broader tool for planning and use this one for the card relationship. That division avoids expecting a single app to provide both issuer access and a complete financial overview.
For a user who wants one application to manage every part of personal finance, I would not make this the first choice. A broader service will likely fit that goal better, while the Ollo app remains useful as a focused account channel. The decision comes down to whether direct card access matters more than an all-in-one dashboard.
Overall, I see Ollo Credit Card Mobile App as a practical, specialized finance app rather than an ambitious financial command center. Merrick Bank has kept the purpose clear: give Ollo cardholders a mobile way to stay connected with their account. Its moderate 3.6 average rating means I would approach it with sensible expectations, but the app’s value is straightforward for the right audience.
My final advice is to judge it by one question: does it make you more likely to check and understand your card regularly? If the answer is yes, the app is worth keeping. If you need cross-account budgeting or detailed financial planning, choose a broader alternative and treat this as optional issuer access. For everyday Ollo card management on a compatible Android phone, I would give it a try, use it alongside good security habits, and keep its limits in mind.
Pros
- Quickly view balances, transactions, and available credit in one place.
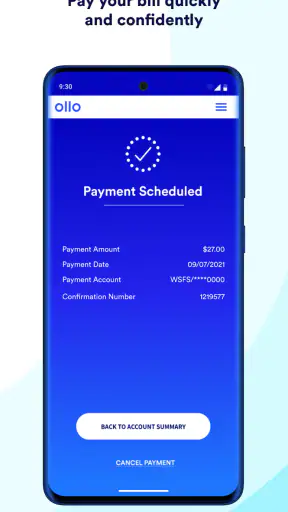
- Payment scheduling helps reduce the risk of missing monthly due dates.
- Real-time alerts can notify you about purchases and account activity.
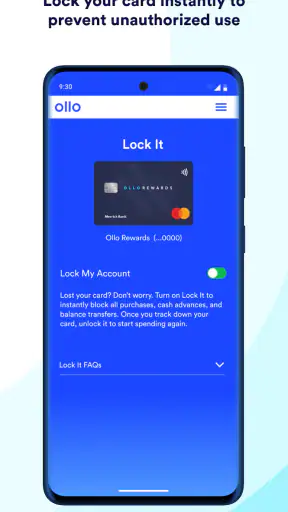
- In-app card controls add convenience when a card is lost or compromised.
- Digital statements make it easier to review spending and payment history.
Cons
- Some account actions may redirect you to a browser instead of staying in the app.
- Support response times can vary, especially for account-specific issues.
- The app is mainly useful to existing Ollo cardholders, not new applicants.
- Older devices may experience slower loading or occasional display issues.
- Limited budgeting tools may not replace a dedicated personal finance app.
FAQs for Ollo Credit Card Mobile App
What is the Ollo Credit Card Mobile App used for?
The Ollo Credit Card Mobile App is designed to help cardholders manage their credit account from an Android or iOS device. After signing in, users can typically review their balance, available credit, recent transactions, payment due date, statements, and account messages. It is intended for existing Ollo card customers rather than people applying for a completely unrelated banking product.
Can I make payments through the Ollo Credit Card app?
Yes, the app is primarily useful for managing payments on an Ollo credit card. Eligible users can generally schedule a one-time payment, review payment activity, and manage available payment information, depending on the account and app version. Before confirming a payment, check the selected bank account, amount, and processing date carefully, since payment timing and posting may vary.
Is the Ollo app safe to use for credit card management?
The Ollo app is intended to provide secure access to your credit card account using account credentials and device-based security features supported by your phone. Users should download it only from the official Google Play Store or Apple App Store, keep the operating system updated, and avoid sharing passwords or verification codes. Never log in through links received in suspicious messages.
Do I need an Ollo credit card to use the application?
In most cases, you need an active Ollo credit card account and valid online account credentials to use the app’s main features. The application is not generally a universal finance manager for cards from other issuers. New users may need to complete registration or account setup before signing in, while existing customers should use the details associated with their Ollo account.
What should I do if the Ollo Credit Card app is not working?
If the application will not open, freezes, or fails to display account information, first check your internet connection and confirm that the app is updated through the official app store. Restarting the device or reinstalling the app may also help, although you should make sure you know your login details first. For locked accounts, payment issues, or persistent errors, contact Ollo customer support through an official channel.

Ollo Credit Card Mobile App
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via merrickmobilesupport@merrickbank.com, visit http://www.ollocard.com, or review their https://www.ollocard.com/resources/privacy-policy/.










